India is one of the world's fastest-growing aviation markets and a significant potential source of carbon credits. Both facts make CORSIA more consequential here than in most jurisdictions — Indian carriers face a steepening obligation, and Indian developers face a demand opportunity gated by a question that is still resolving.
India's Participation
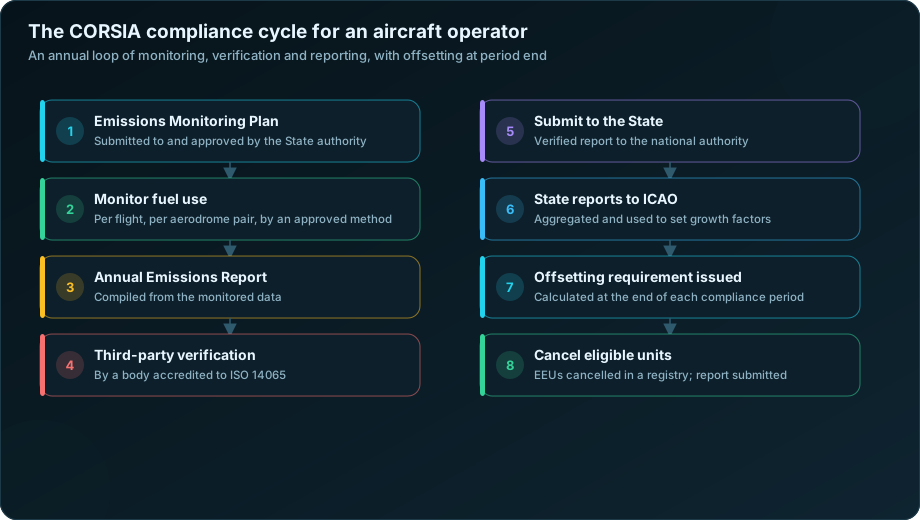
India participates in CORSIA. Indian operators conducting international flights above the 10,000 tonne threshold are in scope, and the Directorate General of Civil Aviation acts as national authority — approving Emissions Monitoring Plans, receiving Annual Emissions Reports, overseeing verification and receiving Emissions Unit Cancellation Reports.
Domestic flights are outside CORSIA entirely. For a carrier with a predominantly domestic network, the in-scope portion may be a modest share of total emissions — but the compliance machinery still has to exist and be maintained.
Why the Obligation Steepens for Indian Carriers
Two structural features of the scheme interact badly with rapid growth.
Route coverage expands in 2027
Second-phase participation becomes mandatory for States above defined aviation activity thresholds. Routes generating no offsetting obligation today, because one end is non-participating, begin to count.
Indian carriers with significant traffic to currently non-participating States will see coverage expand — and the change is entirely network-specific, so a generic percentage uplift will be wrong.
The individual growth factor gains weight from 2033
Obligations through 2032 are calculated purely from sector-wide growth. From 2033 an operator's own growth rate enters the calculation — 15% weight for 2033-2035 under Resolution A41-22.
A carrier expanding faster than the global sector, as several Indian operators are, carries proportionally more of its own burden.
The combined effect is that a carrier's CORSIA cost curve is steeper than its emissions curve. That deserves to be modelled explicitly against fleet and network plans rather than discovered when the invoice arrives.
See baseline and growth factors and CORSIA phases and timeline.
Practical Issues for Indian Operators
| Issue | What to watch |
|---|---|
| Monitoring plan approval | DGCA practice has its own emphases; engage early |
| Data reconciliation | Mixed fleets, multiple fuel suppliers, varying station record-keeping |
| Verifier availability | Limited accredited bodies in the region; demand clusters |
| Registry access and FX | Cross-border payment and treasury questions, resolved before transacting |
| Sustainable aviation fuel | Developing policy and blending targets; claims need full documentation |
Data reconciliation is where the annual effort concentrates
Fuel uplift dockets, flight operations data and finance records need to agree, or their disagreements need documented resolution rules.
For operators with mixed fleets, several fuel suppliers and a range of station-level record-keeping practices, this is the bulk of the work. It is a data engineering problem before it is a carbon problem, and treating it as paperwork is what produces verification findings.
SAF policy is developing
India has been developing SAF policy and blending targets. Qualifying CORSIA Eligible Fuels reduce the offsetting requirement, but the sustainability criteria and chain-of-custody documentation requirements are demanding.
Claiming the reduction requires the paperwork, not just the fuel. See CORSIA Eligible Fuels.
The Position for Indian Project Developers
India has substantial credit-generating potential across renewable energy, energy efficiency, waste management, cookstoves, agriculture and forestry. Whether any of it can reach CORSIA depends almost entirely on one question.
Will India authorise corresponding adjustments?
Under Article 6 of the Paris Agreement, a host State authorising credits for international use must add those tonnes back into its own national accounting, forgoing them against its NDC. For a country with ambitious domestic targets and a large mitigation pipeline, that is a meaningful concession.
India has been developing its own Carbon Credit Trading Scheme under the Energy Conservation Act framework, establishing a domestic compliance market. The government has also signalled a preference for retaining mitigation outcomes domestically in various contexts, and has previously restricted the export of certain credit types.
The interaction between the domestic scheme, Article 6 authorisation and CORSIA eligibility is still being worked through.
What this means practically for a developer
Do not assume authorisation. A project that is technically excellent and fully verified may still be unable to supply CORSIA.
Establish the pathway before committing to a methodology. Domestic scheme participation, voluntary market sale and CORSIA supply are different routes with different requirements. Retrofitting a project onto a different standard later is expensive and sometimes impossible.
Keep a fallback. Building a financial model that only works with CORSIA placement, in a jurisdiction where authorisation is uncertain, is a concentrated bet on a government decision.
Which Indian Project Types Are Better Placed
Assuming the authorisation question can be resolved:
| Type | Outlook | Why |
|---|---|---|
| Waste methane, landfill gas, biogas | Better placed | Clean additionality, no permanence issue |
| Wastewater treatment | Better placed | Same reasoning |
| Industrial energy efficiency | Workable | Additionality depends on the intervention; domestic scheme overlap |
| Cookstoves | Workable with rigour | Large potential, sustained methodological scrutiny |
| Afforestation and forestry | Workable with rigour | Permanence, buffer adequacy, land tenure |
| Agriculture and soil carbon | Difficult | Measurement and permanence immaturity |
| Grid-connected renewables | Difficult | Additionality hard where renewables are least-cost |
The last row matters in India specifically, because utility-scale solar and wind are now frequently the cheapest generation option. That is excellent news generally and very bad news for the additionality argument.
See which carbon projects qualify.
The Timing Argument
Second-phase demand arrives on a known date. A new project typically needs eighteen months to three years from concept to first issuance, with host-State authorisation the least predictable element.
Working backwards from 2027 and the years following: developers who want to serve that demand need to be resolving authorisation now. Waiting until demand is visible means arriving after supply that was already ready has been contracted.
Working With DSTechnoverse
We are an environmental data and analytics consultancy based in Indore, Madhya Pradesh, working with clients across India and internationally. Our CORSIA practice covers both sides — operator compliance and developer market access.
The analytics background matters here. Emissions accounting, growth factor arithmetic, unit due diligence and registry reconciliation are data problems, and data problems are where the costly errors hide. We document reasoning so decisions defend themselves years later to a verifier who was not in the room.
We are also direct about uncertainty. India's authorisation position is genuinely unresolved, programme approvals change, and vintage windows have moved before. Advice presenting any of that as settled is not worth paying for.
See our CORSIA carbon credit services.
Where to Go Next
- What is CORSIA — the fundamentals
- CORSIA scope and thresholds — whether you are in
- National authorities and enforcement — the DGCA's role
- Corresponding adjustments — the developer's gate
Talk to our carbon markets team or apply as a CORSIA buyer or seller.
Further Reading
- CORSIA compliance for Indian airlines
- Your first year of CORSIA compliance
- CORSIA consulting in India
- CORSIA carbon credit services
Frequently Asked Questions
Does CORSIA apply to Indian airlines? Yes for monitoring and reporting: Indian operators with more than 10,000 tonnes of CO2 a year from international flights must monitor, report and verify their emissions to the DGCA. Offsetting obligations depend on which States participate on each route.
Who administers CORSIA in India? The Directorate General of Civil Aviation (DGCA) approves monitoring plans, receives verified emissions reports from Indian operators and reports to ICAO.
When do offsetting obligations become significant for India? From the second phase in 2027, when participation becomes mandatory for States above the aviation activity thresholds, so far more routes, including many to and from India, carry offsetting requirements.
Can Indian carbon projects supply CORSIA credits? Yes, if they are registered with an ICAO-approved programme, fall in the eligible vintage window and, for the first phase, carry host-country authorisation with a corresponding adjustment from India.
What should Indian operators do now? Get monitoring and data systems right, model future offsetting costs under different growth scenarios, and plan credit procurement ahead of the 2027 step-up in coverage.