The ICAO Emissions Unit Criteria (EUC) define what makes a carbon credit usable for CORSIA. A unit satisfies every criterion or it is not eligible — there is no partial credit and no averaging across a portfolio.
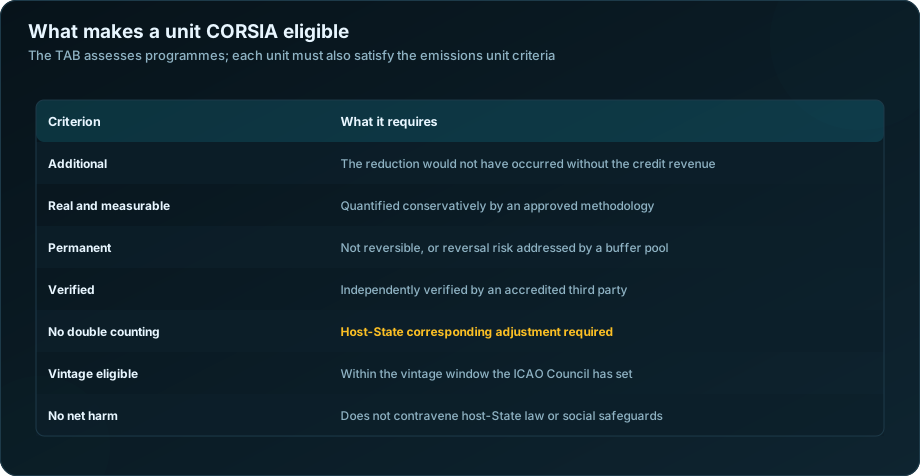
The Criteria at a Glance
| Criterion | Requires | Most common failure |
|---|---|---|
| Additional | Reduction would not have occurred without credit revenue | Renewables in competitive markets |
| Real and measurable | Quantified conservatively under an approved methodology | Monitoring data the project cannot produce |
| Permanent | Not reversible, or reversal risk buffered | Buffer pools sized to historical risk |
| Verified | Independently verified by an accredited body | Verifier capacity, conflicts of interest |
| No double counting | Host-State corresponding adjustment | By far the most common failure |
| Eligible vintage | Within the window for the compliance period | Older inventory ageing out |
| No net harm | No breach of host law or social/environmental safeguards | Land tenure disputes |
| Traceable | Unique serialisation, clear registry record | Buyer's own record keeping |
Additionality
The reduction must not have happened anyway. If the activity was already profitable, already legally required, or already common practice, paying for it buys nothing.
Evidence: a plausible baseline scenario, an investment or barrier analysis showing why carbon revenue was needed, and a common practice test showing the technology is not already the norm in that context.
Where it fails, and why it has got harder
Additionality is the most contested criterion in the entire carbon market.
Grid-connected renewables are the standard example. The argument that a solar farm needed carbon revenue was straightforward in 2012 and is very hard to sustain in a market where solar is now the least-cost generation option. Several programmes have narrowed or retired methodologies for exactly this reason.
The practical consequence for developers: a project design that would have passed a decade ago may not pass now, and past success with a methodology does not transfer.
Real, Measurable and Conservatively Quantified
The reduction must have physically occurred, be quantifiable under a defined methodology, and be calculated with assumptions erring toward under-crediting.
Evidence: an approved methodology, a monitoring plan defining exactly what is measured and how, calibrated equipment where relevant, and documented calculations.
Where it fails — usually monitoring, not arithmetic
The methodology may require data at a frequency or granularity the project cannot actually produce over its lifetime. Equipment fails and is not replaced promptly. Field staff turn over, taking undocumented knowledge with them.
Conservative quantification means resolving genuine uncertainty toward fewer credits. Cookstove projects have faced sustained scrutiny over usage assumptions; forestry projects over baseline deforestation rates. Projects that resolved uncertainty in the other direction have been challenged, sometimes successfully.
Permanence
For emissions avoided, permanence is straightforward — a tonne not emitted stays not emitted. For carbon stored in biomass or soil it is not: forests burn, are logged, or die.
Evidence: buffer pool contribution holding credits in reserve against reversals, long-term monitoring commitments, and legal or contractual protection of the carbon stock.
Where it fails: buffer adequacy is under active scrutiny as wildfire and drought losses accumulate. A buffer sized against historical risk may be undersized against current risk. This is a live methodological question, not a settled one.
Independent Third-Party Verification
A qualified body independent of the developer must verify that the reductions occurred as claimed.
Evidence: a verification report from a body accredited under the programme's rules, covering a defined monitoring period, with any qualifications explicitly stated.
Where it fails: verifier capacity is a genuine constraint — accredited bodies are limited and queues form. Conflict of interest rules also bite: the body that validated a project design frequently cannot verify its performance.
No Double Counting
The same reduction must not be claimed twice. This criterion eliminates more supply than all the others combined.
Three forms:
| Form | What happens | Prevented by |
|---|---|---|
| Double issuance | Two credits for one reduction | Registry controls |
| Double use | One credit retired twice | Unique serialisation |
| Double claiming | Host State counts it toward its NDC while an airline counts it toward CORSIA | Corresponding adjustment |
The third is the hard one, and the remedy is a formal authorisation from the host State together with an adjustment to its own national accounting.
Evidence: an authorisation document from the designated national authority, referencing the specific units, plus evidence of the adjustment in national reporting.
Where it fails: constantly. Governments must weigh investment and revenue against a harder path to their own targets. Many decline. Others lack the machinery entirely — no designated authority, no process, no precedent.
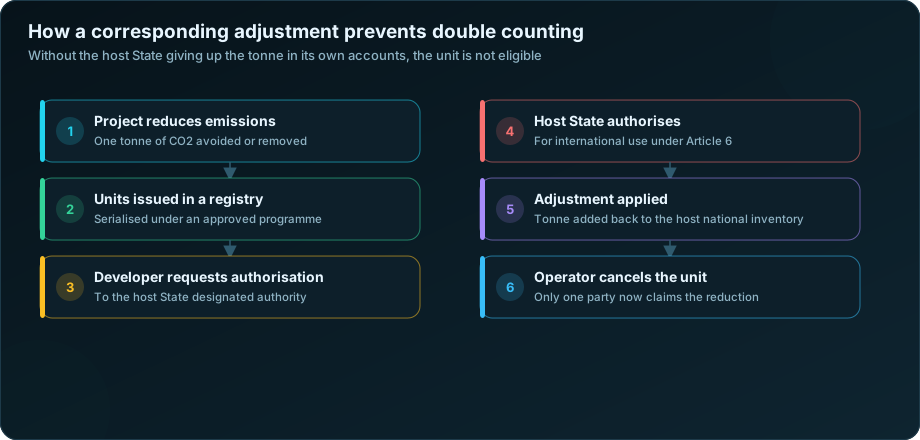
Covered in full in corresponding adjustments and Article 6.
Eligible Vintage
The reduction must have occurred within a vintage window the ICAO Council has designated for the relevant compliance period.
Evidence: the registry record showing the monitoring period in which the reduction occurred. Note that the issuance date is not the vintage — a unit issued last year may carry a much older vintage.
Where it fails: older inventory ages out. Windows have been adjusted before, so units near a boundary carry real risk. See vintages and eligibility windows.
No Net Harm
The project must not contravene host-State law and must not cause social or environmental harm.
Evidence: environmental and social impact assessment, stakeholder consultation records, free prior and informed consent where indigenous or local communities are affected, and a functioning grievance mechanism.
Where it fails: land tenure disputes, particularly in forestry. Agreement from a government or a large landholder is not the same as consent from the communities actually using the land, and projects that conflated the two have faced sustained challenge.
Registry Traceability
Units must be uniquely serialised and held in a registry with transparent issuance, transfer and cancellation records.
Evidence: registry records showing the full chain of custody through to cancellation.
Where it fails: rarely at the registry level — those systems are generally sound. Failures occur in the buyer's own record keeping, where the evidence package cannot be reassembled three years later when a verifier asks.
The Practical Buyer Sequence
- 1Programme currently approved? Full or conditional?
- 2If conditional, does the condition touch these units?
- 3Vintage inside the window for your compliance period?
- 4Host-State authorisation document naming these units?
- 5Corresponding adjustment applied, or only committed?
- 6Verification report from an accredited body, qualifications examined?
- 7Registry chain of custody clean, no prior retirement?
- 8Full package captured in your own files, not linked?
If any answer is uncertain, resolve it before transacting. A cheap unit that proves ineligible is the most expensive unit you can buy.
Where to Go Next
- CORSIA Eligible Emissions Units — the definition
- Approved crediting programmes — the programme layer
- Corresponding adjustments — the binding constraint
- Registries and cancellation — traceability in practice
The criteria are published by ICAO.
DSTechnoverse runs criterion-by-criterion due diligence before you transact. Get in touch.
Further Reading
- Verifying CORSIA eligibility: a buyer workflow
- Which carbon projects qualify for CORSIA
- CORSIA carbon credit services
Frequently Asked Questions
What are the CORSIA emissions unit criteria? ICAO's requirements that crediting programmes and their units must meet: additionality, a realistic baseline, quantification, monitoring and verification, clear ownership, permanence, leakage controls, avoidance of double counting, and no net harm.
Who checks programmes against the criteria? ICAO's Technical Advisory Body assesses crediting programmes and recommends approval to the ICAO Council.
What does additionality mean for CORSIA? The reductions would not have happened without the incentive from carbon credits, beyond what law or business-as-usual would have delivered.
How is double counting prevented? Units are cancelled only once and tracked in registries, and for the first phase they carry a corresponding adjustment by the host country so the reduction is not also counted towards its national target.
Do the criteria apply to each unit? Programme approval is the first layer; individual units must also meet the conditions in ICAO's eligibility decision, such as vintage windows and authorisation.